capital gains account scheme hdfc bank

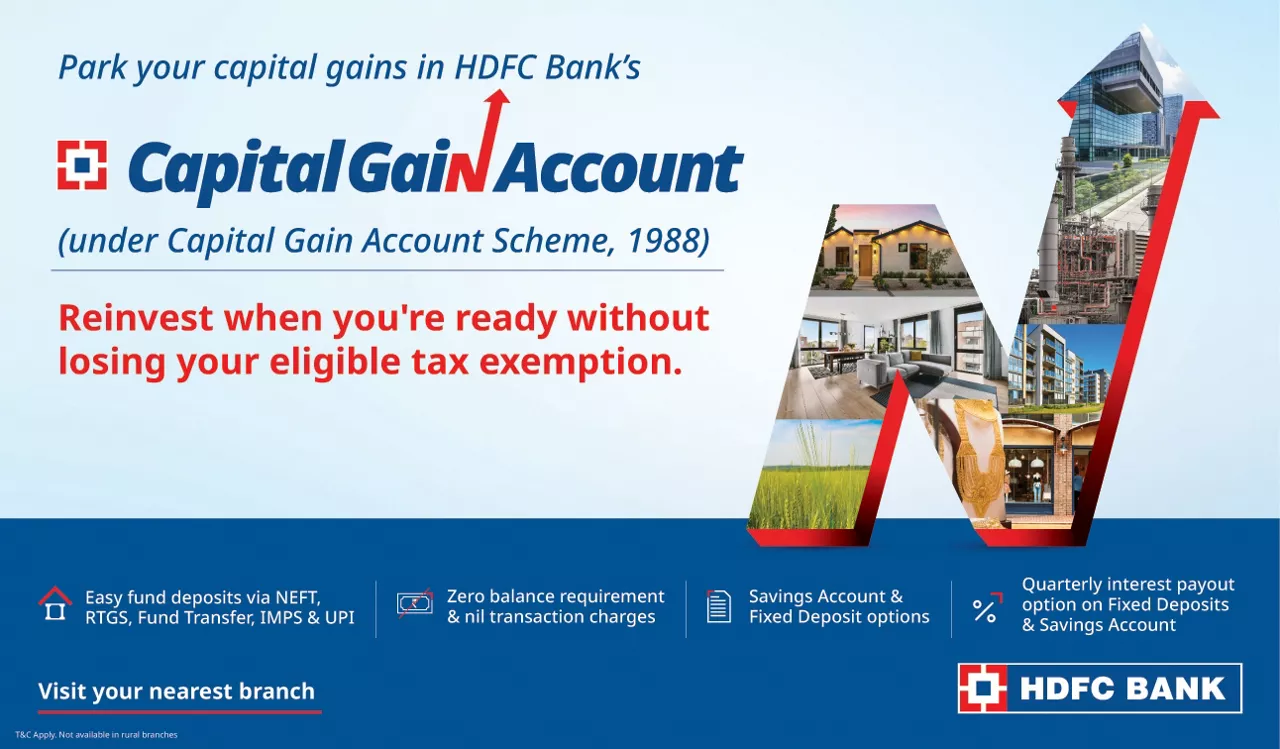
When you’ve sold a property, land, or other qualifying asset but need more time to reinvest, CGAS offers a compliant way to temporarily hold your capital gains/net consideration upto a maximum of 3 years* without losing potential tax exemption under applicable Income Tax sections.

Please consult your tax advisor for eligibility and applicable sections. HDFC Bank does not provide tax advisory.

*Terms and conditions apply

Key Benefits

Wondering If You Are Eligible?

To open Capital Gains Scheme Savings Account (account- A), you must meet one of the following eligibility criteria:

  • Resident Individuals including Minors
    (Minor account will be operated by guardian)
  • Hindu Undivided Family (HUFs)
  • Sole Proprietorship Firms
  • Partnership Firms
  • Companies
Startup Current Account


Documents required to get you started

Applicable to All Customers:

  • Form A - Application to open Capital Gains Scheme Savings Account
  • Proof of Asset Transfer (e.g. Copy of registered sales deed/transfer deed)
  • Chartered Accountant certified Capital Gain Computation Sheet
  • Individual / Non-Individual Account Opening Form

Additional documents for New Customers:

  • KYC documents as per constitution and profile

Additional Information for Existing Customers:

  • KYC compliant Customer ID

About Capital Gains Accounts Scheme

  • Account / Fixed Deposit Ownership
  • No joint holding allowed
     

  • Nomination (for Individual customer only)
  • Upto 3 allowed. Minimum 1 nomination mandatory while opening the account
     

  • FD Rate of Interest
  • Prevailing interest rate applicable as per tenure and amount

  • No additional interest rate benefit for Senior Citizen / Staff

  •       Note: For FD Interest rates click here

  • Restrictions
  • Debit Card/ATM Card, Cheque Book are not issued.
  • No cash deposits or withdrawals allowed
  • FD sweep‑in/out & auto‑renewal not available
  • No Overdraft/Loan allowed on FD
  • Online transactions not permitted (view-only access available)
  • Funds withdrawn but unutilised to be re-deposited within 60 days as per applicable rules.

  • Account Closure
  • Account closure allowed only with Income Tax office approval and only through home branch
     

  • Time Limit for New Asset Investment (from date of transfer/compulsory acquisition)
  • Section 82: Purchase - within 2 years, Construction - within 3 years
  • Section 83: Purchase - within 2 years
  • Section 84: Purchase / Construction - within 3 years
  • Section 86: Purchase - within 2 years, Construction - within 3 years
  • Section 87: Purchase / Construction - within 3 years
  • Section 88: Purchase / Construction - within 3 years

  • Most Important Terms & Condition
  • Click here for T&C apply
     

  • Application Process
  • Please connect with your Relationship Manager or visit a branch (expect rural branch)

  • They will guide you on the next steps

  • Disclaimer
  • HDFC Bank does not provide tax advisory services. Customers are advised to consult their tax advisors for eligibility, applicable Income Tax section, and reinvestment guidance. All features, processes and timelines are governed by the Capital Gains Accounts Scheme (CGAS), 1988 and amendments issued by the Government of India along with Bank's guidelines.
More About Capital Gains Accounts Scheme

Account / Fixed Deposit Ownership

  • No joint holding allowed
Card Reward and Redemption

Nomination (for Individual customer only)

  • Upto 3 allowed. Minimum 1 nomination mandatory while opening the account
Redemption Limit

FD Rate of Interest

  • Prevailing interest rate applicable as per tenure and amount (no differential interest rate for bulk deposits).
  • No additional interest rate benefit for Senior Citizen / Staff
Redemption Limit

Deliverables

  • Debit Card/ATM Card, Cheque Book are not issued
Redemption Limit

Account Closure

  • Account closure allowed only with Income Tax office approval and only through home branch
Redemption Limit

Time Limit for New Asset Investment (from date of transfer/acquisition)

  • 2 years - Purchase (Section 82/86), Section 83
  • 3 years - Construction (Section 82 / 86), Section 84, Section 87, Section 88
Redemption Limit

Most Important Terms & Condition

  • Click here for T&C apply.
Redemption Limit

Application Process

  • Please connect with your Relationship Manager or visit a branch (expect rural branch).
  • They will guide you on the next steps.
Redemption Limit

Frequently Asked Questions

What is the Capital Gains Accounts Scheme?

Capital Gains Accounts Scheme (CGAS), 1988 is designed for Individuals, HUF & Non-Individuals who wish to defer tax liability on Capital Gains by depositing the gains in designated accounts until used for eligible purposes as specified under the Scheme.

Under which section gains can be deposited?

Gains to be deposited basis renumbered section (as per Income Tax Act, 2025).
 

Sections of Income Tax
Renumbered Sections (as per Income Tax Act, 2025) 82 83 84 86 87 88
Erstwhile Sections (as per Income Tax Act, 1961) 54 54B 54D 54F 54G 54GA


HDFC Bank does not provide tax advisory services. Customers are advised to consult their tax advisors for eligibility, applicable Income Tax section, and reinvestment guidance. All features, processes and timelines are governed by the Capital Gains Accounts Scheme (CGAS), 1988 and amendments issued by the Government of India along with Bank's guidelines.

Who can deposit in the Capital Gains Accounts Scheme?

Resident Individuals, HUF & Non-Individuals such as Sole Proprietorship, Partnership firms & Companies who have Capital Gains as per above section. 

In case of jointly owned assets, each co-owner must open a separate CGAS account corresponding to their share of Capital Gains.
 

Which is the qualifying asset considered for Capital Gains Accounts Scheme?

  • Section 82: Residential House Property (Apartment / Building / Land).
  • Section 83: Agricultural land.
  • Section 86: Any Capital Asset other than residential house property (e.g.: Gold/ Jewellery, Shares/Securities, Artifacts).
  • Section 84: Land or building forming part of an Industrial undertaking transferred by way of compulsory acquisition.
  • Section 87: Plant, machinery, land, or building (purpose of an industrial undertaking) situated in an urban area which is shifting to a non-urban area
  • Section 88: Plant, machinery, land, or building, or any right in land or building used for the purpose of an industrial undertaking situated in an urban area which is shifting to SEZ (Special Economic Zone).
     

Which is the New Asset to be purchased?

  • Section 82: Residential House Property (Apartment / Building / Land).
  • Section 83: Agricultural land.
  • Section 86: Residential House Property (Apartment / Building / Land).
  • Section 84: Land or building for the purposes of shifting or re-establishing undertaking or setting up another industrial undertaking.
  • Section 87: New plant or machinery, Purchase or Construct a building, acquire land, shift the original asset into a non-urban area.
  • Section 88: New plant or machinery, purchase or construct a building, acquire land, shifting original asset in SEZ (Special Economic Zone)
     

What is the time limit to deposit in Capital Gains Accounts Scheme?

You have to deposit your gains on or before due date of filing IT returns.
 

How much can I invest in the Capital Gains Accounts Scheme?

Section 82 & 86 have a limit of ₹10 Crore.

For other sections (83, 84, 87, 88), there is no upper limit defined at present.
 

How long can we keep money in a Capital Gains Accounts Scheme?

You cannot exceed 2 to 3 years from the date of transfer of original asset. Time Limit for New Investment :

  • Section 82: Purchase: 2 years. Construction: 3 years from date of transfer
  • Section 83: Within 2 years after date of transfer of original asset
  • Section 86: Purchase: 2 years. Construction: 3 years from date of transfer
  • Section 84: Within period of 3 years after the date of compulsory acquisition
  • Section 87: Within 3 years after the date of transfer
  • Section 88: Within 3 years after the date of transfer
     

Can Capital Gains Accounts Scheme (CGAS) be transferred between banks?

No. CGAS cannot be transferred between banks.
 

Is interest earned in the Capital Gains Accounts Scheme taxable?

Interest payment is subject to Tax Deducted at source (TDS) as per prevailing Income Tax Act.
 

What types of accounts are opened under Capital Gains Accounts Scheme?

You can deposit your Capital Gains in Capital Gains Scheme Savings Account (account - A) and Capital Gains Scheme Fixed Deposit (account - B).

Capital Gains Scheme Savings Account (account- A) is mandatory.

Can a Current Account be opened?

No.

Can a new customer open Capital Gains Scheme Savings Account (account A)?

You can open Capital Gains Scheme Savings Account (account - A) by providing required documentation.

Can a joint account be opened?

No. You cannot open joint account under this scheme.

Can multiple accounts be opened under Capital Gains Account Scheme?

Yes, you can open multiple Captial Gains Scheme Savings Account (account - A) as per eligibility under various income tax sections.

Can a Standalone Fixed Deposit be opened?

No. Capital Gains Scheme Saving Account (account - A) is mandatory to open Capital Gains Scheme Fixed Deposit (account - B).

Whether the deposit can be made in instalments?

You can deposit the funds via NEFT, RTGS, Funds Transfer, IMPS & UPI either in lumpsum or in instalments on or before the IT return filing due date.

What are the interest options in Deposits?

You can open term deposit under Cumulative or Non-Cumulative option.

  • In Cumulative FD, the Interest reinvested (paid only on maturity).
  • In Non-Cumulative FD, the interest is paid on quarterly basis & credited to Capital Gains Scheme Saving Account (account - A)
     

What are the documents required to open Capital Gains Scheme Savings Account (account - A)?

PAN, Form A, Proof of Asset Transfer, Chartered Accountant certified Capital Gains Computation Sheet and Individual / Non-Individual Account Opening Form are mandatory documents. Also, basis customer's banking relation (New or Existing Customer) KYC documents will be required.

Who can have nomination & how many?

An individual can have a maximum of three nominees, and at least one nominee is mandatory at the time of account opening; nomination is not permitted for minors, HUF, or non‑individual entities.

How to open a Capital Gains Scheme Savings Account (account - A)?

Capital Gains Scheme Savings Account (account - A) can be opened by visiting the nearest HDFC branch (except in "Rural Branch") along with the required documents.

Which branches can open Capital Gains Scheme Savings Account (account - A)?

All Branches except "Rural Branches" can open Capital Gains Scheme Savings Account (account - A)

Can Capital Gains Accounts Scheme be transferred between HDFC branch?

Yes. CGAS can be transferred to any other HDFC bank branch (except in rural branch).

What is the rate of interest offered to the customer?

For Capital Gains Scheme Savings Account (account - A): Prevailing interest rates for SB Accounts.

For Capital Gains Scheme FD (account - B): HDFC Bank’s prevailing FD rates.
 

Can I get special interest rates on FD?

No. There are no differential interest rates on any category. (e.g.: Senior Citizen, Staff).
 

Can the FD be used as collateral for Lending/ Overdraft/ Loan facility?

No.

How will I receive the Interest payout?

Interest payouts are in two types:

  • Cumulative FD - Interest are reinvested & paid only on maturity.
  • In Non-Cumulative FD, the interest is paid on quarterly basis.

    In both the payouts, Interest is credited to Capital Gains Scheme Saving Account (account - A)
 

Is premature FD closure allowed?

Yes. But only as per guidelines mentioned in Capital Gains Accounts Scheme and the Bank’s FD premature closure policy. Penalty will be applicable as per Bank’s policy.
 

How is TDS calculation done?

TDS shall be deducted as per the existing Income Tax guidelines. The procedure will be same as domestic Fixed Deposits and exempt upto the ceiling limit under specific section.
 

Can I get exemption on TDS?

If you are an eligible customer for TDS exemption, please submit Form No 121 (earlier known as 15G/15H) as per extant guidelines.
 

How do I check transaction in my account?

You will be issued passbook / statement where all particulars such as amount deposited, withdrawn, interest paid, etc. will be noted.

Also, you can view your account details online via net banking and mobile banking.
 

Which deliverables are not offered under Capital Gains Scheme Savings Account (account - A) ?

Cheque Book and Debit Card /ATM Card are not issued to customer.

  • FD sweep‑in/out & auto‑renewal not available
  • No cash deposits or withdrawals allowed
     

Is Online Banking available?

Net Banking & Mobile Banking is available with only viewing rights.
 

How do I withdraw funds from the Capital Gains Accounts Scheme?

Funds can be withdrawn from Capital Gains Scheme Savings Account (account - A) furnishing form ‘C’. After first withdrawal, subsequent withdrawals to be done via both Form 'C' and 'D'.
 

In how many days the funds must be utilised?

The money must be used within 60 days after withdrawal for the purpose as mentioned in the specific section.
 

What if there is no complete utilisation of funds withdrawn?

The unutilised funds must be redeposited in the Capital Gains Scheme Savings Account (account - A) within 60 days of withdrawal. Non-compliance of this rule will render the depositor to lose exemption for the withdrawal amount done under that section & will not be allowed to further deposit in the Capital Gains Scheme Savings Account (account - A)
 

Going forward, how can I make subsequent withdrawals?

You can do subsequent withdrawal by giving form 'C' & form ‘D’ where details to be included for utilization & purpose for which the previous withdrawal has been done.
 

Can I break Capital Gains Scheme Savings  FD (account - B) and transfer funds to Capital Gains Scheme Savings Account (account - A)?

Yes. Premature / partial withdrawal from Capital Gains Scheme FD (account - B) is permitted via Form B.
 

Can I modify nomination?

Yes, you can do the same by applying through the existing nomination form
 

How can I close the Capital Gains Scheme Saving Account (account - A)?

You can close the account via application in Form ‘G’ with the approval of Income tax Assessing Officer who has jurisdiction to the assessee depositor.

Once the approval is obtained, the same is required to be submitted to the Bank for account closure.
 

In event of account holder death, what should a nominee / legal heir do?

If depositor is deceased, the nominee will make application in Form ‘H’ for approval of Income Tax Assessing Officer (having jurisdiction over deceased assessee depositor).

If there is no nomination, then legal heirs will apply in form ‘H’ for the approval of Assessing Officer (having jurisdiction over deceased assessee depositor).

Once the approval is obtained, the same is required to be submitted to the Bank for account closure.